We're so confident of our products that we provide no hassle product exchange.


CIMA F2 Exam Overview:
| Certification Vendor: | CIMA (Chartered Institute of Management Accountants) |
|---|---|
| Exam Name: | Advanced Financial Reporting |
| Exam Number: | F2 |
| Exam Format: | Multiple Choice Questions, Objective Test (OT), Computer-Based Exam |
| Exam Duration: | 90 minutes |
| Related Certifications: | CIMA Management Level CIMA E2 Enterprise Management CIMA P2 Advanced Management Accounting |
| Passing Score: | 100/150 (scaled score) |
| Certificate Validity Period: | No fixed expiry for individual exam pass; counts toward full CIMA qualification progression |
| Exam Price: | Varies by region (approximately GBP 120–180) |
| Available Languages: | English |
| Real Exam Qty: | 60 (objective test, multiple choice) |
| Recommended Training: | CGMA Official Learning Resources Kaplan CIMA Courses BPP CIMA Training |
| Exam Registration: | CIMA Exam Booking CIMA Official Qualification Information |
| Sample Questions: | CIMA F2 Sample Questions |
| Exam Way: | Computer-based exam delivered via Pearson VUE test centers and online proctoring where available |
| Pre Condition: | No strict prerequisite; typically taken within CIMA Management Level (E2, P2, F2) progression after or alongside Operational Level |
| Official Syllabus URL: | https://www.cimaglobal.com/Qualifications/CIMA-Professional-Qualification/ |
CIMA F2 Exam Syllabus Topics:
| Section | Objectives |
|---|---|
| Specialised Financial Reporting Topics | - Events after reporting period - Changes in accounting policies and estimates - Financial instruments |
| Financial Reporting Framework | - Regulatory environment and standards (IFRS overview) - Conceptual framework of financial reporting |
| Group Financial Statements | - Associates and joint arrangements - Business combinations - Consolidated financial statements |
| Interpretation of Financial Statements | - Performance evaluation - Financial ratio analysis |
| Financial Statements | - Statement of cash flows - Preparation and presentation of financial statements |
CIMA Advanced Financial Reporting Sample Questions:
In the year ended 31 December 20X7, FG leased a piece of machinery. The accountant of FG had prepared the financial statements for the year to 31 December 20X7 on the basis of the lease being an operating lease.
However, following the end of year audit it has been agreed that the machinery is in fact held under a finance lease and therefore the financial statements need to be corrected.
The correction will have which THREE of the following affects on the financial statements?
- A. Current liabilities will increase.
- B. Non-current assets will increase.
- C. Non-current assets will decrease.
- D. Depreciation costs will decrease.
- E. Non-current liabilities will decrease.
- F. Finance costs will increase.
Correct Answer: A,B,F 🗳️
What is the total comprehensive income attributable to the non-controlling interest that will be presented in GHI's consolidated statement of changes in equity for the year ended 31 December 20X4?
- A. $190,000
- B. $575,000
- C. $595,000
- D. $95,000
Correct Answer: D 🗳️
Information from the financial statements of RST for the year ended 30 April 20X9 is as follows: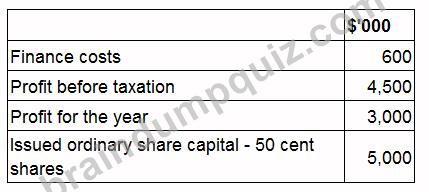
At 30 April 20X9 the ordinary shares are trading at $4.75.
What is the price earnings (P/E) ratio for RST at 30 April 20X9?
- A. 9.31
- B. 7.92
- C. 15.83
- D. 10.56
Correct Answer: C 🗳️
LM acquired 15% of the equity share capital of ST on 1 January 20X6 for $18 million. LM acquired a further 50% of the equity share capital of ST for $50 million on 1 January 20X7 when the fair value of ST's net assets was $82 million. The original 15% investment in ST had a fair value of $20 million at 1 January 20X7. The non controlling interest in ST was measured at its fair value of $30 million at the date control in ST was acquired.
Calculate the goodwill arising on the acquisition of ST that LM included in its consolidated financial statements at 31 December 20X7.
Give your answer to the nearest $ million.
$ ? million
Correct Answer:
18, 18000000
FGH plans to issue a large number of shares to the public via an IPO.
It is considering either an offer for sale at a fixed price or an offer for sale by tender.
Which of the following would be an advantage to FGH of using the offer for sale by tender compared to the fixed price offer?
- A. The shares will be sold to different investors at differing values thus maximising the capital raised.
- B. Tenders are more attractive to less sophisticated investors thus maximising potential investment.
- C. There would be more certainty over the issue price of the shares.
- D. There is potential for reaching a higher share price thus maximising capital raised.
Correct Answer: D 🗳️
Viewing page 1 out of 43 pages.
Viewing questions 1-5 out of 212 questions.
 By Magee